Merger Arb: 23% Upside (at C$1.26)
This is a fairly curious merger arb case, which offers a substantial 23% spread to the all-cash offer. The shareholder vote is set for August (no exact date yet), with closing probably to follow soon after. That said, I have some reservations about this setup and would be keen to hear the opinions of other SSI members.
Banxa provides B2B software that enables crypto conversions. In simple terms, it helps businesses convert fiat to crypto and back, while handling compliance with local laws. It’s one of the main players in the space, with a client base that includes major crypto wallets and exchanges, such as Circle, MetaMask, Ledger, and OKX.
A few days ago, Banxa agreed to be acquired by OSL Group for C$1.55/share in cash. The transaction still needs to be approved by shareholders (33% are already in support) and regulators.
It is not hard to see why Banxa might be an attractive business to bid for. Crypto is hot again—the industry is seeing strong tailwinds and growing demand. Regulators worldwide are advancing its adoption. Last month, the US Senate passed a stablecoin bill that sets a regulatory framework for issuing digital assets backed by fiat reserves. A similar bill is set to take effect in Hong Kong this August. These moves are expected to open the door for banks and institutions to issue their own stablecoins, which could significantly accelerate the growth of crypto and in turn demand for conversion from fiat to crypto.
One of Banxa’s core strengths is its global regulatory footprint, which includes US, UK, Canada, Brazil, and others. These licenses are notoriously difficult and time-consuming to obtain. In the US alone, the process took two years. Meanwhile, UK crypto license is handed out to only 7% of total applicants. I suspect that these licenses, combined with established relationships with leading industry players, are a key reason for the acquisition.
The buyer, Hong Kong listed OSL Group with a US$1.2bn market cap, has global ambitions. It operates a fully regulated crypto exchange and has been vocal about its plans to expand into crypto payments and cross-border transactions. Lately, it’s been on a global shopping spree, buying small crypto businesses with various licenses across difference geographies. Recent acquisitions include CoinBest in Japan (2024), and certain entities in Europe (Lithuania and Italy, 2024) and Indonesia (2025). It also secured a license in Australia and aims to file applications in three more jurisdictions this year.
OSL appears to be well connected within the Chinese government. Its main shareholder is BGX, which holds a 30% stake and whose co-founder previously served as chairman and CEO of OSL. Last year, he was appointed by the government to a special ‘Task Force on Promoting Web3 Development‘ under the Financial Services and Treasury Bureau. OSL has also partnered with one of the biggest Chinese funds (ChinaAMC) to launch crypto ETFs.
I do not expect any regulatory pushback. Although a Chinese buyer adds some uncertainty to the regulatory review process, especially given the current geopolitical climate, the approvals in this case seem manageable. Crypto payments is not a sensitive sector and the market is highly competitive, which is why Banxa still hasn’t been able to turn profitable yet. The business is also relatively small (~C$100m EV).
Shareholder approval is also likely to be secured. The current 33% support roughly matches insider ownership on a non-diluted basis. All of Banxa’s options, warrants, and the convertible note are currently well in the money. On a fully diluted basis, management and the founder (who seems to be running the show) hold a combined 46% stake. That ownership alone would be close to securing the vote. Admittedly, it’s still unclear if management will be considered to be interested parties (approval by disinterested shareholders will also be required).
In terms of valuation, the company is unprofitable and not growing. On TTM gross profit basis the buyout values Banxa at 3.6x. That does not seem expensive for a crypto infrastructure business positioned to benefit from strong industry tailwinds (peers operating in the space are private, so relative comparison is hard). In any case, I think this merger is mostly about Banxa’s licenses and technology rather than its recent operating performance.
That’s more or less the bullish pitch for BNXA merger arb.
My reservations about this setup
There are likely several reasons behind the current spread, and most of them are quite difficult to handicap.
#1: The entire buyout saga has been quite messy:
- Banxa launched a strategic review in 2022, contacting over 150 potential buyers and signing 21 NDAs. However, only one non-binding offer was submitted, with no terms disclosed.
- A bit later, a few other bidders showed up with offers in C$0.50–C$1/share range, but nothing materialized out of that.
- In December’24, BNXA’s insiders launched a privatization offer at C$1/share. The special committee approved the offer, and binding documents were signed.
- At the beginning of February, Exodus Movement (sizeable US crypto firm) submitted a much higher competing offer, valued at C$1.79/share in cash and stock. Management deemed it as superior.
- A few weeks later, the “superior” offer simply expired after the parties failed to agree on final terms.
- The following day (February 18), the original management-led privatization was canceled. The board chairman was replaced, and the chair of the special committee resigned.
- In April, Banxa disclosed new interest from another party, with an indicative range of C$1–C$2/share, but there have been no further updates since.
- On June 27, the current sale to OSL Group was announced.
BNXA’s management certainly doesn’t come out looking great, between the clearly lowballed privatization attempt and the failed negotiations with a superior bidder.
Another concern is that plenty of parties have looked at Banxa over the years, but very few have shown serious interest. Most of the offers received were well below the current bid. That puts a dent in the ‘high-demand business with valuable licenses’ thesis. However, with Trump’s administration actively promoting crypto and creating tailwinds for the sector, it might really be different this time.
BNXA’s new chairman is a former Member of the European Parliament who later became a crypto entrepreneur. He is also a well-known professional poker player, Tony G. He increased his stake in BNXA to 9% (fully diluted) at around C$1.50/share during the management-led privatization attempt. After that transaction collapsed, he was suddenly appointed chairman of the board. At the time, he said, “I believe the market is undervaluing its potential. I see immense long-term growth ahead and I’m backing this with action by becoming the second-largest shareholder.” Just a few months later in April, he reduced his stake to 7%, when the stock was trading at just C$0.65/share.
#2: The man behind the wheel at Banxa is Domenic Carosa, who is the founder, ex-chairman and current largest shareholder (~13.6% diluted stake). His background is ‘somewhat colorful’. He has been involved in a lawsuit related to the bankruptcy of crypto lender Cred. Carosa was accused of colluding with Cred’s executives to submit a sham bid during the early bankruptcy process in order to access its trade secrets and intellectual property. He then allegedly ‘smuggled’ that IP into another company, leaving Cred’s creditors with nothing. Carosa’s involvement alone probably explains a significant part of the spread.
#3: Strange fluctuations in shareholder support. Previous management privatization at C$1/share had backing from 53% of shareholders. However, the transaction was eventually cancelled due to “overwhelming sentiment expressed by Banxa securityholders in recent weeks that Banxa should remain a public company”. Most likely, shareholders simply changed their minds once they saw a much higher competing bid from Exodus. However, the current offer from OSL at C$1.55/share comes at a similar premium and is also fully in cash. So it’s unclear why this time only 33% of shareholders are in support (most of which are probably insiders themselves). This might signal that shareholder vote could be more problematic than it seems. However, I still think it’s a small risk overall.
#4: The termination fee is set at 5% of the transaction value, which is higher than the typical 2–3% range seen in most M&A deals. This might reflect that both sides see elevated risks to close the transaction. For comparison, Banxa’s privatization attempt just six months ago included a termination fee of only 2.7%.
#5: Lastly, the downside is difficult to pinpoint but could be significant. Before the management-led privatization attempt in December, the stock was trading at around C$0.75/share, implying a potential 40% drop from the current levels. More recently, prior to the OSL bid, the stock was trading around C$0.85/share, suggesting 33% potential downside.
A bit more on business background
BNXA has two revenue streams:
- Agency transactions, in which it connects fiat/crypto buyers and sellers and earns a commission;
- Principal transactions, in which BNXA supplies the crypto/fiat itself, takes inventory risk, and books the full gross transaction value as revenue.
This makes the top line messy, so that is why gross profit is a better metric for the valuation.
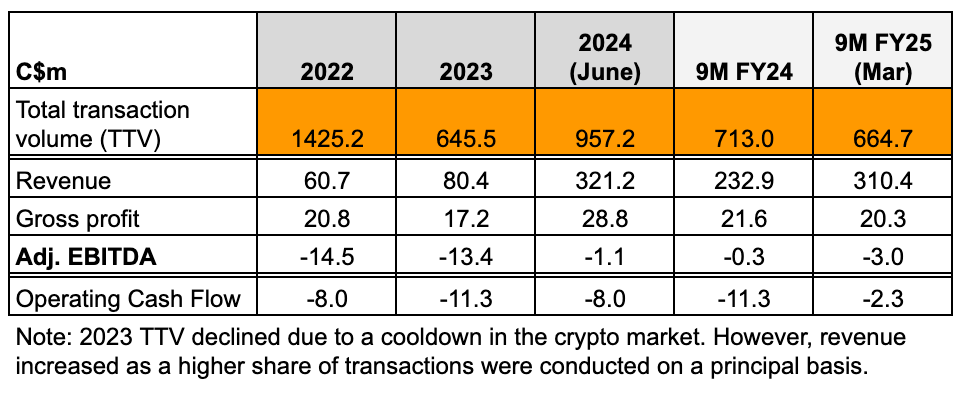
Quick historical financials can be seen in the table below. The story is straightforward: the business was booming in 2021–2022, slumped during the crypto bust in 2023, and has been recovering steadily since.
This trade 100% comes down to the Chinese buyer and Canada’s Net Benefit review to determine, through a national security review, whether there will be an issue. The country has been vocal about about Chinese buyers being heavily scrutinized and have previous seen deals have problems purely on this element. Any details you have on this element should form the basis of the risk/reward on this trade.
Below are the stated “Required Regulatory Approvals” as per OSL’s filing. Interestingly, it seems that the Canadian ones won’t even be required, only EU (Dutch), UK and US.
“the declaration of no objection from the Dutch Central Bank (De Nederlandsche Bank) (DNB) in accordance with Regulation (EU) 2023/1114 on markets in crypto-assets; the approval from the U.K. Financial Conduct Authority; and the receipt of the regulatory approvals relating to each U.S. Money Transmitter License of Banxa or its subsidiaries to be obtained in connection with the consummation of the transactions contemplated by the Arrangement Agreement and documents referred to therein”
https://www1.hkexnews.hk/listedco/listconews/sehk/2025/0627/2025062703766.pdf
I would add that there are some explicit conditions to the deal closing:
“(i) EU Internet Ventures B.V. shall have obtained a license as crypto asset service
provider under Regulation (EU) 2023/1114 on markets in crypto-assets (‘‘MiCAR’’)
with the proper authorizations for all crypto asset services required for the conduct of
all its business activities from the Netherlands Authority for Financial Markets
(Autoriteit Financiële Markten); and (ii) any person holding a qualifying holding as
defined in Article 3(1)(36) MiCAR in EU Internet Ventures B.V. (or that will acquire a
qualifying holding as contemplated by the transactions contemplated by the
Arrangement Agreement) shall have obtained a declaration of no objection or
comparable approvals from the Dutch Central Bank (De Nederlandsche Bank) (DNB)
pursuant to Article 83 MiCAR;”
As far as I can see Banxa had a transitional license in Europe that expired on June 30, 2025 and as long as they don’t have a license under the new MiCAR framework (and I don’t see them in the register: https://www.afm.nl/nl-nl/sector/registers/vergunningenregisters/cryptopartijen) they’re not allowed to offer their services in Europe. Could be a nothing burger but also a deal breaker.
And also:
“rights of dissent shall not have been exercised with respect to more than 5% of the issued and outstanding Banxa Shares;” .
Given the history of the company and the actors involved I don’ think it is impossible that one of these ‘colorful characters’ dissents.
That said, OSL stock reacted positively to this deal, so as long as the regulatory hurdle is met I think there could be a decent chance of this deal closing.
Thank you for the additional details. As for the EU MiCAR license, it does not appear to be a major hurdle. As you mentioned, the company already held an EU license before the recent regulatory update. On BNXA’s November 2024 conference call, management said they expected the new license to be granted in the first half of 2025, so it should be arriving soon. The fact that both parties proceeded with signing the deal instead of waiting suggests they are confident it will come through. Management also previously attempted to take the company private without waiting for the license.
From November call:
As for the dissent condition, it’s hard to see why anyone would actually want to trigger it. Management seems genuinely inclined to sell. If they were actually aiming to take the company private, they could’ve just pushed ahead with the earlier privatization attempt, i.e. bumped the price, etc. Instead, they signed this deal with OSL. So unless they have some ‘4D chess’ moves planned behind the scenes, it doesn’t make sense to derail the process now. Other than that, these dissent conditions are waivable (I’ve seen that happen before) and OSL has retained the right to waive it as well.
actually, OSL group only had about 600m HK dollars. Most of the cash will cost for this buyout.
I just concerned the deal may not be such stable.
The consideration is HK$486.7m, to be funded through a mix of cash on hand and some external financing. It’s a highly strategic acquisition that has been very well received by OSL’s shareholders (the stock has been rising since the announcement). Given the buyer’s HK$11.8bn market cap, the deal is relatively small. It is also not subject to a financing condition.
The spread has increased to 31%, although I don’t see any news. It’s getting more attractive, but downside from these levels could still be very substantial.
Domenico Carosa (former chairman and the man behind the wheel) sold 40k shares at C$1.24/share on July 14. That doesn’t look great given the pending takeover at C$1.55/share. The market may also be growing concerned that the shareholder meeting date still hasn’t been announced, even though the vote is expected in August.
https://www.marketbeat.com/instant-alerts/banxa-holdings-inc-cvebnxa-insider-domenico-carosa-sells-40400-shares-2025-07-14/
It was much more than 40k shares.
He sold 282k shares between July 7 to July 17 at C$1.24-1.25/share, for C$350k.
However, he owned 11.8m shares before the recent dispositions.
Selling only 2.4% of his total stake seems very strange if he indeed has a negative view. It may has something to do with some pre-arranged disposition plan?
2.4% so far. It’s an illiquid stock and his sales were a big part of the trading volume on the days he sold. He might not have been able to sell more. We also don’t know when he may have developed a negative view. There is a pending EU license application in the final stage of the approval process.
They looked like pre-brokered block trades. On the days he sold, no large price impacts were visible from the tape.
Carosa has stopped selling for now.
It could have just been an urgent need for some quick cash to buy $FARTCOIN or something.
Spread now stands at 37%
A minor correction: vote is not expected in August. Instead, the circular and the notice of EGM is expected to be dispatched in August.
“A circular containing, among other things, further details of the Proposed Acquisition, and a notice of EGM and other information as required under the Listing Rules is expected to be despatched to the Shareholders on or before 31 August 2025 as additional time is required to prepare the information for inclusion in the circular.”
Sorry I misunderstood. The Banxa shareholder vote is indeed expected in August.
The OSL Group shareholder vote is expected after August.
I am curious why such a small acquisition (US$62m on a fully diluted basis) would need buyer shareholder approval as well.
The buyer, OSL Group, has a market cap of US$1.5 billion.
OSL Group has classified it as a major transaction. Under HK listing rules if any of 5 percentage ratios (14.07) acquiree/acquirer defined in the rules are between 25% and 100% (14.06) then it’s a major transaction that requires shareholder approval. One of those 5 is a revenue ratio. That’s probably what triggers it. Banxa revenue is even higher than OSL’s (would be Very Substantial Acquisition) but they may have adjusted it down because it appears Banxa recognizes revenue on a gross basis and OSL on net basis. Banxa gross profit to OSL revenue is between 25% and 100%.
OSL Group did a US$300m private placement equity raise recently and mentioned the Banxa acquisition as one of the uses for this.
Looks like a done deal. What risks are the market seeing, for a 25% spread?
Beyond what DT and writser outlined above, I don’t know. It makes no sense to me that the man behind the wheel is leaving a 24% spread (over a short holding period) on the table by selling shares now. Where else is he deploying that capital where it’s going to earn more? If he’s so desperate for cash, why not borrow?
On the other hand it trades really weird and volatile. One morning it just randomly opened at $1.08 on low volume and quickly recovered.
@Matt Just my personal observation: folks involved in crypto rarely have much cash on hand, always deploy every penny (including borrowing capacity) and encounter opportunties (e.g., defi lending) that can potentially earn >25% within a short period of time.
Proxy has been mailed out, shareholder meeting to be held on August 28
Spread of 26% remains very wide.
Carosa continues selling
Just have a question – so looks like Crown Research, indirectly wholly owned by Mr. Liu Shuai, who also owns BGX, which is 30% owner of OSL, holds 29.95% of the BNXA. Is that 29.95% included in 33% supporting group? If so, that indicates very minimum insiders in the supporting group. Otherwise that would represent >50% in the shareholder group who would support the deal.
https://www1.hkexnews.hk/listedco/listconews/sehk/2025/0627/2025062703766.pdf
Where does it say that? The document you referenced says the opposite in the 2nd paragraph of the 2nd page.
Crown owns 29.95% of OSL, not BNXA.
Oh ok, I misunderstood. That makes sense now, so both OSL and BNXA secured ~30% votings in the shareholder group.
No, the 33% supporting group does not contain Crown (But it does contain Carosa who initially pledged 5.6mn shares but now is only left with 5.2mn shares?). You can find the shareholding group:
https://www.sedarplus.ca/csa-party/records/document.html?id=a3cad7325b387759b6b57931eadd920aacfd05302175ddcc55aaf68aaaa6b9bd
https://www.sedarplus.ca/csa-party/records/document.html?id=06770fa843aec6f98bd4ca4cc56416bdf1e1b0041a99afd2c06260b04584070a
https://www.sedarplus.ca/csa-party/records/document.html?id=459a381d019d5359fb302a792d5dc8b296ce9c5ba3261ddb9bb64e0e0b19641a
Interestingly, in the Arrangement Agreement released by Banxa on 27 June, they wrote that there was “No related party” who owns >1% of outstanding shares. I’m unsure why this is the case given that Crown Research should be considered an interested party.
Scenario 1 – Crown Research isn’t considered an interested party
66.67% (Required votes) – 33% (Supporting Group) – 30% (Crown Research) = 3.67%. required more votes out of 37% (Remaining Shareholders 100% – 33% – 30%) = Which works out to be only about 8% of remainder votes.
Scenario 2 – Crown Research deemed as Interested party. Require 66.67% of disinterested shares to push vote through
70% (Disinterested Shareholders) * 66.67% = 46.69% (Required votes)
46.69% – 33% (Supporting Group) = 13.69% required more votes out of 37% (Remaining shareholders) = Which works out to be around 37% of remainder votes.
Could someone kindly check my math and let me know if my understanding of the situation is correct?
MiCAR status: As of 7 Aug 2025 (latest version available) I don’t see EU Internet Ventures B.V. in the AFM CASP register. BNXA/EUIV says it applied in Nov 2024 (https://support.banxa.com/en/support/solutions/articles/44002649169-eu-internet-ventures-b-v-and-micar). AFM guides that, even in a best case, a CASP licence takes at least five months (https://www.afm.nl/en/sector/cryptopartijen/vereisten-en-vergunningen/casp-vergunning). Management had anticipated H1’25 – clearly didn’t happen.
I’m pretty sure MiCAR (plus the governance hair others have flagged) is what’s driving the spread.
Side note: management’s own comments underline how heavy this is (“licenses are always a big process… 140 documents for MiCA”). That frustration with regulation may also explain Carosa’s selling.
Timing: From complete filings, MiCAR/AFM/DNB + FCA + US MTLs could still take 3–6 months. I’m using H1’26 as base duration.
UK/US:
– FCA change in control: typically 3-6 months from a complete notification (https://www.fca.org.uk/firms/change-control).
– US MTL change of control: many states clear in 30-60 days, but the slowest state gates overall timing (overview: https://www.goodwinlaw.com/en/insights/publications/2023/08/insights-finance-ftec-the-fintech-deal-long-pole). BNXA’s US licence list: https://banxa.com/wp-content/uploads/2025/04/BNXA-USA-MTL-Inc-_-Website-Licenses-as-of-04.10.2025.pdf
Spread/probability: At ~26% spread and assuming downside CAD 0.75-0.85, the implied close probability is roughly 54-60%, which feels low. I think the true odds are higher than 60%, but I don’t expect a quick timetable.
Tempted to size up now and trim after the BNXA vote clears and OSL’s EGM is set, waiting for MiCAR to clear (I’d expect real spread compression only thereafter).
As expected, shareholder approval has been received. Interestingly, the spread has narrowed to just 12% after the announcement. Various regulatory consents remain outstanding. Management anticipates closing in Q4’25-Q1’26.
https://www.sedarplus.ca/csa-party/records/document.html?id=7bde59fdcc3336183c83df50641d64ae86ec1aeae0d24654676962c99270f1e7
OSL Group missed its deadline for sending out the circular and EGM notice on or before 31 August 2025. No extension has been communicated either.
AFAIK it’s an expected target date, not a hard legal deadline, but it adds timeline risk until they put out an update. I have written IR, they already should have a waiver or make a “delay in despatch” announcement.
As additional time is required to prepare and finalise the information to be contained in the
Circular, it is expected that the despatch date of the Circular will be postponed to a date
falling on or before 30 September 2025.
The “delay in despatch” announcement was published.
BNXA issued an update on the merger:
1) Change of control approval has been received in 17 out of 37 designated U.S. states.
2) The company has received the declaration of no objection from the Netherlands De Nederlandsche Bank. Banxa calls this a “key milestone” toward receiving the full MiCAR license from the Netherlands.
3) UK FCA approval is underway.
4) The final court hearing to approve the arrangement, originally set for September 2, 2025, has been adjourned “by order of the Supreme Court of British Columbia to give the parties additional
time to obtain the remaining Required Regulatory Approvals.”
https://www.sedarplus.ca/csa-party/records/document.html?id=5a8d815e262294cfb2970d3b0d454ed2e514375c37cf743eb1eb5ed61a4b84b9
I just curious who stay the same situation like me…….received the coporation action notice and tender all the stock to the company……then found I couldn’t sold the stock…….asked IB then reply me I only could wait for they send money to my account after the deal close. so strange that I first met this situation after I experienced so many tender offer and buyout deals. Be frankly I didnt think twice after I saw the tender offer noticement……..blame myself……..
Price is now back down to C$1.16/share (33-34% upside)
The stock is up 14% today because EU Internet Ventures B.V. finally got its EU license. I think some risk remains purely because the industry is unpredictable and volatile and the buyer may change its mind and very cheaply get out of the deal if it wants to.
What’s the cost if OSL gets out of the deal?
The termination fee payable by OSL is C$4.25m. While this represents a relatively high ~5% of the transaction value, the amount is quite small for the acquirer ($1.6bn market cap). Note also that the buyer might potentially walk away from the transaction after the December 29 outside date.
The whole deal is worth just US$60m. As much as we can say it costs very little (as % of OSL’s market cap) to walk away, we can also say it costs very little for OSL to complete the deal.
The owner of OSL benefits mostly from the appreciation of OSL stocks. If acquiring Banxa can make OSL a hotter crypto stock in the eyes of the market, OSL stock rising by 5% can already more than pay for the $60m acquisition.
Carosa has continued selling now at this higher stock price since the EU license was obtained.
BNXA filed FY25 results. Regulatory approvals in 11 out of 37 U.S. states remain outstanding, the same as in the last update from several weeks ago. Probably the process has been halted during the shutdown. There has been some progress on the U.K. regulatory approval front, with the company receiving the first round of questions on its application submitted to the FCA. The spread is 23%.
The shutdown affects only the federal gov, not the state level agencies.
BNXA meeting to approve the merger “has been further adjourned due to scheduling and administrative issues” from 6 Nov to 20 Nov.
“The Company and OSL continue to pursue certain outstanding required regulatory approvals (as described in the Company’s news release dated October 27, 2025), pending the date of the new hearing.”
Is this purely due to “scheduling and administrative issues”? or are they having issues securing votes?
My mistake. Shareholder approval has already been obtained in August, so the hearing is purely to finalize the merger and it has been adjourned twice for pending regulatory approvals.
FWIW, when it was adjourned for the first time in September, the PR didn’t give a new hearing date (which was late announced on 27 Oct to be 6 Nov).
On this second adjournment, a new date is specified. However, unlike the PR on 10 Oct, expected timeline for US states approvals and UK approval is not indicated.
I hope the short adjournment (2 weeks) is a positive sign that management expects that the finish line is very close.
Any news re the final order hearing that was supposed to have taken place on 20 Nov (last Thursday)?
A lot of volatility today but I couldn’t find any news or press release from the company.
Update on Banxa’s regulatory approval situation:
– Change of control approvals for money-transmitter licenses have been received in 35 out of 37 US states, compared with 26 as of late October.
– Documentation for license change of control has been submitted to Netherlands regulators.
– UK review is ongoing. OSL Group has responded to all questions raised thus far by the UK regulator, the FCA.
https://www.sedarplus.ca/csa-party/records/document.html?id=1cc151bdbd717663df47ef3a76f4e2eba419c39221d4dbb2725adb1fd8bc1b4e
BNXA went up +15% yesterday on very positive takeover update. The closing is now expected in a few weeks. 4% spread remains.
BNXA has secured the critical regulatory approvals from the UK Financial Conduct Authority and the Dutch De Nederlandsche Bank. In the US, change of control approvals have been received in 36 of 37 designated states. The single outstanding state approval is expected shortly, though OSL Group retains the right to waive this condition to force closing.
The parties have set an effective date of January 2, 2026. The outside date has been extended to January 29, 2026, to accommodate the final steps. With the waiver option available for the last state approval, this transaction is basically de-risked.
https://www.sedarplus.ca/csa-party/records/document.html?id=936373174c64d808254103a64853f4c2ba7638dc8bf7056c370e570911fd12e8
The spread has been eliminated. This has played out nicely, although the ride was quite volatile, with the spread widening to 40%+ a few times. I’m removing BNXA from active cases with +23% return in 6 months.
Very nice, but a bumpy ride, indeed!