Current Price: $24.35
Target Price: $43+
Upside: 75%
Expected Timeline: 1-6 months
I first covered STAAR Surgical back in September (see here). What started as a relatively straightforward setup with an ongoing takeover, shareholder activism and a shot at a higher offer has morphed into a prolonged and increasingly bizarre saga. The situation seems to be nearing a turning point. After a few recent developments and a pullback in the share price, I think the risk/reward has improved and the setup is attractive again.
Here is the quick version of the story so far:
- STAAR Surgical is a global leader in phakic intraocular lenses, which are implanted between the iris and the natural lens to treat myopia.
- In April 2024, industry giant Alcon privately made a non-binding $58/share offer for STAAR.
- In October 2024, Alcon amended the offer to $55/share plus a CVR worth up to $7 ($62 in total). Management allowed due diligence.
- Shortly after, STAAR’s China sales fell off a cliff, going from around half of total sales to almost zero. The share price fell from ~$40 in mid-2024 to $18. Alcon walked away.
- Management said the China issues would be temporary and were mainly driven by channel stuffing and inventory imbalances. The market wasn’t buying it.
- In July of this year, Alcon suddenly returned with a non-binding $27/share offer, which was quickly raised to $28/share. These offers were also not disclosed to the public at the time.
- Negotiations moved fast, and on August 5, STAAR announced a definitive merger agreement at $28/share.
- The very next day, STAAR released its Q2 results, which included the guidance: “We expect our China revenue will normalize in the second half of fiscal 2025, as our distributors increase their purchases of ICLs to meet forecasted demand.”
- Broadwood Partners (owns a 30% stake) and Yunqi Capital (5%) opposed the takeover. They argued that China sales would normalize soon and that Alcon was trying to opportunistically snatch STAAR at a massive discount. Activists also noted that the sale process was flawed, as STAAR engaged only with Alcon and gave very limited time / basically ignored to the two other interested parties that had reached out independently.
- It was clear that the transaction would be blocked by shareholders. According to Yunqi, a total of 72% of outstanding STAAR shares were opposing the offer. All three major proxy advisory firms also recommended to vote against the deal.
- The shareholder meeting date was adjourned several times from the initial October 23.
- Last month, Q3’25 results delivered a massive rebound of China sales (from almost zero to 60% of normalized levels), supporting the activists’ case.
- Also last month, Alcon proposed that STAAR run a 30-day go-shop process. 21 potential buyers were contacted. The process was completed several days ago, but no competing bids emerged.
And now this week brought a couple of new developments:
- Alcon bumped its bid by 10% to $30.75/share.
- Broadwood and Yunqi promptly rejected it, saying the price is still far too low, and that the recent go-shop process was structured to seal the Alcon deal, not to maximize value for shareholders.
From Broadwood’s response:
The belated and appended go-shop process was not designed in a manner to attract qualified bidders and proposals: interested parties were asked to sign off-market, multi-year standstills (unlike Alcon itself, which never signed a standstill); had to subject their proposed terms to Alcon’s over-the-shoulder inspection and unilateral matching rights; and were given just days to engage with the Company.Yunqi also added:
A 30-day period is too short to support a meaningful market check for a company with STAAR’s global distribution footprint, regulatory complexity, and manufacturing profile. Any credible strategic or financial acquirer would require time to analyze regulatory conditions across multiple jurisdictions, assess pricing dynamics in key markets, conduct due-diligence on manufacturing, supply chain, and growth forecasts, coordinate consortium or financing partners, and obtain board or investment-committee approvals.
The spread to the new $30.75 offer now stands at 26%. I think that’s a good moment to get involved as the saga nears a turning point, and, most importantly, the downside should be limited regardless of which direction we turn next (there are quite a few possible directions). Pre-announcement price is $18/share, but that was with China sales hovering closer to zero for 3 quarters in a row and with market having lost any trust in management’s recovery promises. Since then, China sales are back to 60% of the previous levels, Alcon put a price tag on the company and activists started pushing for managerial changes to improve shareholder value. So even if the merger with Alcon breaks, I do not think STAAR will sell off all the way to the pre-announcement levels. I would expect the downside to be limited to 10-15%.
In a way, STAAR is a bit of a black box for investors without inside knowledge of the boardroom discussions. We now have two versions of what might be happening both in terms of its China operations and the integrity of the recent go-shop. Broadwood and Alcon hold entirely opposing views on these points, and in the end, it is difficult to judge whether Alcon is simply trying to snatch STAAR at an opportunistic moment or genuinely believes it’s offering a fair price. The only thing we can be sure of is that Alcon really wants to own this business.
Broadwood’s stance is that China sales will recover quickly and that STAAR should be worth something closer to what Alcon was willing to pay last year ($58/share-$62/share). The activist appears genuinely confident in that view. Just a few weeks ago, it bought another 1.5m shares in the $27/share-$28/share range. Broadwood has been invested in STAAR for about 30 years, so it should know the company well. At this point, it is hard to argue that the activists are merely bluffing about their conviction in the China rebound. Broadwood’s take on the go-shop is outlined in the quote above as well as on slide 13 here. The essence is that it was designed in a way that effectively deterred other interested parties from properly engaging with management.
Alcon, on the other hand, argues that the business has been structurally impaired and that China sales will not return to prior levels. It has done a fair amount of posturing to underscore this position. It refused to raise its offer for an extended period, issued a presentation on it’s “perspective” on the situation, proposed a go-shop, and despite massive shareholder pushback has delivered only a modest bump so far. Alcon is an industry giant that should clearly understand STAAR’s business dynamics. It can also now point to the failed go-shop as further leverage in arguing that its offer is the best and only one available.
The go-shop situation is actually interesting and a little funny. STAAR’s management responded to the activists by pushing back on the idea that any credible bidders had shown up. To make that point, it chose to disclose that one of the parties was FountainVest, a well-capitalized Chinese private equity firm, but noted that it approached STAAR only on the 21st day of the go-shop and that NDA negotiations consumed almost all of the remaining time. Management tried to “set the record straight” by framing this as something like “FountainVest was not a serious bidder as it would have engaged earlier otherwise.” In reality, I think this disclosure only proved the activists’ point – credible suitors were indeed involved, but the go-shop was simply too short and too heavily conditioned for any party to properly explore an acquisition.
Shareholder vote on the new Alcon’s offer is now set for December 19.
Broadwood is now working to call a special meeting to reshuffle the board and install directors who would run a properly designed sale process (one that activists expect would yield a far superior offer). If the takeover gets blocked, activists succeed in replacing the board and STAAR’s China sales rebound to previous levels the upside could be substantial (~70%). But even if Alcon is right and the next earnings report disappoints, the downside will most likely be relatively contained (10-15% or so).
Here are the 4 main scenarios that could unfold from here:
- Alcon raises its bid again, creating a quick win.
- The takeover is voted down, activists reshuffle the board and relaunch a sale process later in 2026.
- The current offer is approved.
- The current meeting date is delayed again.
Let’s take a closer look at each of them.
Scenario #1: Alcon raises the bid again
Despite what is implied in the wide current spread, I don’t think another bump from Alcon is completely off the table. There are multiple aspects that suggest Alcon could still improve the bid to try and salvage the buyout:
- Alcon clearly wants to buy STAAR. It has been circling the company for almost two years and has made multiple offers. Despite significant shareholder pushback on the current price, Alcon did not let the deal collapse and agreed to multiple amendments, including several shareholder meeting date adjustments.
- Alcon has already raised its offer once after insisting for a long time that $28 was the best STAAR could hope for.
- Importantly, the buyer did not say the improved $30.75 offer is final. The gates are fully open for further raises.
- The transaction is highly strategic, though small in terms of overall size for Alcon. I covered the background in my earlier write-up, but the core point is simple: STAAR’s phakic IOLs is a product that Alcon doesn’t have yet, and which is rapidly taking share from Alcon’s legacy laser procedures. STAAR is already dominant in Asia, with 70% share in Japan and 20% in China before the collapse. It had been compounding revenue at 25% until the China issues surfaced. For Alcon, the acquisition closes a major portfolio gap and protects its refractive surgery position as patient preferences shift. It also gives Alcon a chance to accelerate US adoption of STAAR’s lenses through its entrenched commercial infrastructure (STAAR has tiny market share in US). Alcon’s CEO confirmed that as well:
I think the acquisition of STAAR represents an opportunity for us to take STAAR places they haven’t been able to go, won’t be able to kind of finance on their own. So, I think we can scale that company and create a lot of synergy around it.
- To be honest, I am not even sure Alcon cares much about STAAR’s China sales. It may simply be using that as negotiating leverage. What Alcon really wants is the technology, the IP, and the ability to scale it quickly in the US.
Viewed this way, there might be a pretty decent chance Alcon will not let the current bid slip through its fingers.
This outcome would be the fastest and cleanest way to win here, and I think the market might be underrating the odds.
If you’re only interested in playing this specific scenario (short-term bet on a bid raise over the next several weeks), the downside should be protected very well. If Alcon doesn’t raise and the takeover is voted down (signaling shareholder confidence in a higher value), it’s difficult to believe the stock would drop significantly from current levels – at least until the next quarterly results come out in January. Broadwood made a similar point (slide 21) after Q2 results, when meaningfully stronger Q3 numbers were not even out yet.
Scenario #2: The takeover is voted down
If the current takeover is blocked, activists reshuffle the board, STAAR’s China sales normalize, and a properly run sale process follows later in 2026, the upside from current levels could be substantial.
One reference point for the STAAR’s value is Alcon’s offers before the China issues began: $58/share in April 2024 and $55/share plus a $7 CVR in October 2024.
Another reference point is relative valuation. The revised Alcon offer values STAAR at 3.7x 2027E revenues. Broadwood argues that based on STAAR’s projected revenue growth and margins relative to medtech peers, the multiple should be closer to 5.3x-5.5x. That would imply a price target of $43-$45/share, with 75%+ upside from current levels. This price target is in line with STAAR’s trading levels in mid-2024, before China issues began.

The main drawback of this extended “retry the sale under Broadwood’s control” scenario is that it largely comes down to trusting the activists on STAAR’s China sales normalization.
STAA’s preliminary Q4 results should be announced in January 2026. Strong results would significantly increase the odds of reaching high-upside outcome. However, if the results disappoint, the activists’ thesis could be harmed.
As mentioned earlier, STAAR is a black box in this regard, and I can only guess what Q4 numbers will be. Still, a number of high-level signals point to a higher likelihood of positive results than negative:
- Before Alcon’s bid, management repeatedly said the China issues were temporary.
- Q2 report guided for sales normalization in H2’25.
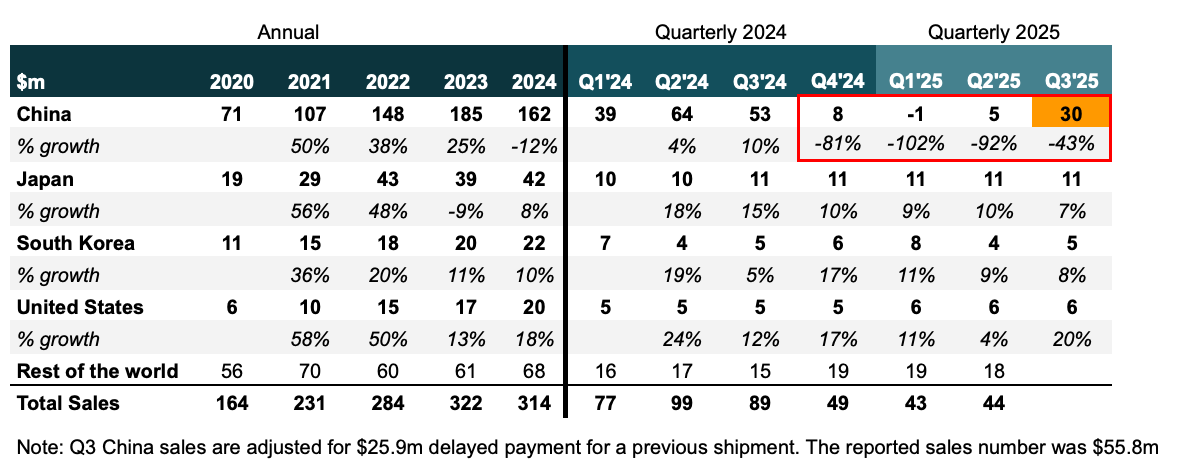
- Performance in Q3 confirmed that guidance. See the historical performance table below.
- Interestingly, STAAR’s management tried to bury the lead – Q3 preliminary figures excluded China sales entirely, and the full results barely mentioned them at all. This behavior is just super odd. If the quarter had been a one-off outlier or if previous guidance was no longer valid because the business was actually permanently impaired, they could have simply said so. Instead, it looks more like they were trying to downplay a genuine recovery that might undermine Alcon’s offer.
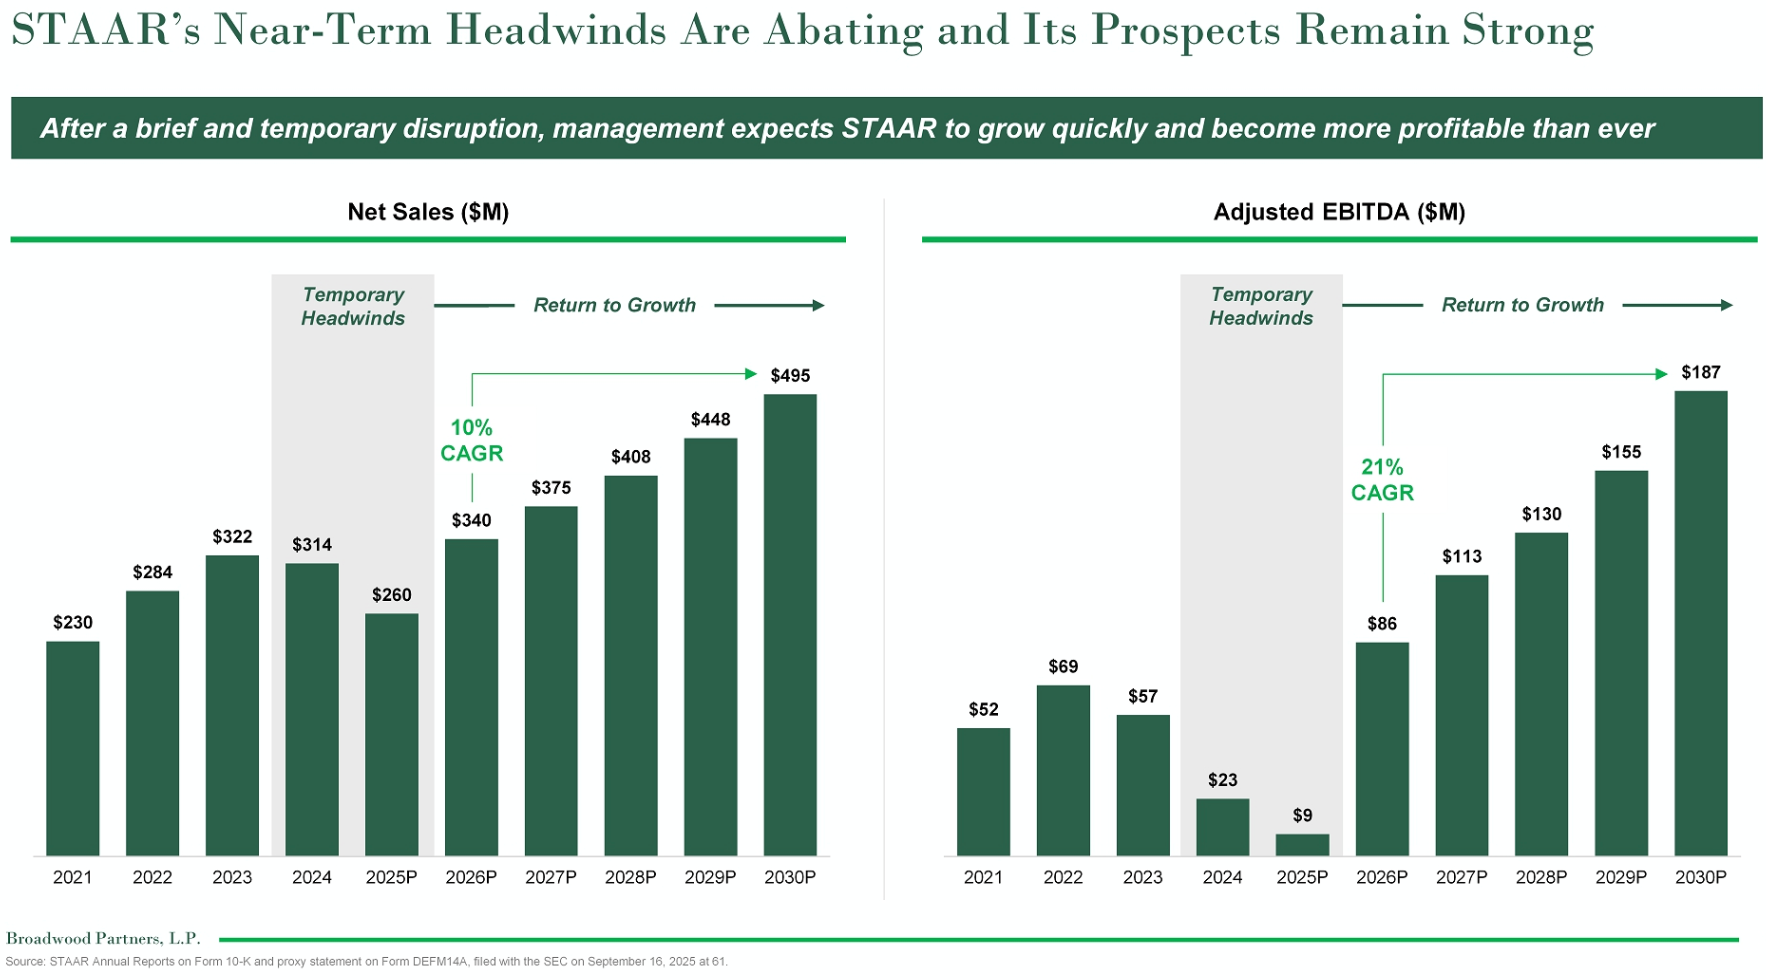
- September’s proxy included management’s financial projections that showed STAAR returning to sales and profitability growth from next year (Broadwood’s presentation):
- Broadwood seems very confident in the rebound given it increased its position in STAA by $40m last month.
- Alcon is clearly in close contact with STAAR management, and Q4 is almost over. Putting on a small tin foil hat, one could speculate that the buyer should be pretty well aware of the ongoing business trends at STAA. From this perspective, Alcon’s decision to raise the offer (and not call it final) after a failed go-shop process, could also suggest the business is going in the right direction.
So despite having zero visibility into the current situation in China, I’m comfortable enough to stand alongside the activists and betting on the rebound.
If Q4 results end up slightly disappointing (i.e. China sales are stable / in line with Q3, but full normalization will take longer than expected), the downside should remain limited, especially given the prospects of management change and activists taking control.
The numbers would need to be genuinely terrible, implying real long-term business impairment, for the share price to drop to or below pre-announcement levels. Based on everything we know so far, that appears unlikely. In the worst case, activists could simply re-engage with Alcon and try to bring it back to the table at a similar or slightly lower price.
So overall, this longer post-deal-break scenario presents an asymmetric opportunity.
Scenario #3: The current offer is approved
This is the least likely path. With 35% opposition from Broadwood and Yunqi, almost 80% of the remaining shareholders would need to approve the current offer for it to pass. Still, a small chance remains. The failed go-shop and the modest bump could give proxy firms just enough cover to issue favorable recommendations, and sway other minority holders as well.
Even if this scenario materializes, it would not be a bad result from current levels, delivering more than 20% upside in just a few weeks.
Scenario #4: The current meeting date is delayed again
This path could also expose investors to the preliminary Q4 numbers, which should arrive in January. So it also requires some confidence in the activists’ thesis of sales rebound. If the results are good, the stock will likely rally above the current offer as/and the odds of Alcon raising its bid would increase materially. That could mean a 25% to 30% return in a month, with additional upside optionality on higher offers.
If the Q4 results are released before shareholders vote on Alcon’s offer, and the numbers come in weak, activists may revise their price expectations and become more willing to support a sale to Alcon. Even in that case, the outcome would likely still yield a modest return from current levels.
Additional notes on the activists
- Broadwood Capital runs a very long-term, highly concentrated portfolio (only 12 public positions). STAAR is their third-largest holding at roughly a 22% allocation. Their track record with core positions is very strong: Monster Beverage, owned since 2009, is a 17-bagger; Axon Enterprise, held since 2017, is a 30-bagger. STAA is a 5-bagger for now.
- Yunqi Capital is a small hedge fund based in Hong Kong. STAA is their largest public position, with a 39% allocation. It’s interesting that Yunqi sold its previous stake in STAA just after the offer announcement, but then promptly reacquired the stake at ~$28/share and now holds 5.1%.
- Broadwood has also set up a website for its campaign, where more detail on its arguments can be found: www.letstaarshine.com
Closest Opex happens to be Dec 19 and these options are definitely not priced for fireworks – one way or another. Very cheap way to get in lower levels by selling puts with some juice in them, or buy cheap 25Cs for upside if Alcon shows why last offer wasn’t best and final.
Friday offered a good opportunity to achieve lower entry level via options. I created a position in my IRA so I needed to buy stock/sell calls (as opposed to simply selling puts). I sold the Dec19 $25 strikes and created the long at $22.83. I tend to believe that the meeting date will either be delayed or the vote won’t succeed if it is held.
New here, looking at last quarter sales, a large part of the ramp up in revenue was a one time book from 2024 from deferred payments?? If this is the case, how can anyone point to a China rebound. Again, just asking as I am looking at this one closely
The point is that even after adjusting for the one-time impact of the deferred payments, the revenue rebound was significant. Please refer to the historical financials table in the write-up above.
Proxy advisor Glass Lewis is advising that shareholders reject the 30.75 bid… hence the drop on Friday
From Alcon PR Dec 9, 2025 8:30 AM Eastern Standard Time stated offer is best and final. Still these are not set in stone and a revised offer with a substantial CVR added or similar can be offered.
The amended transaction provides tremendous value to STAAR stockholders, while providing an exciting opportunity for Alcon to broaden the access to STAAR’s leading technology to benefit patients around the world,” said David Endicott, Chief Executive Officer of Alcon. “This best and final offer to the STAAR stockholders offers a clear choice: a substantial and certain premium versus an uncertain future tied to a dissident activist with a dubious track record.”
Thanks Prabhu. There’s some good evidence what happens when I don’t do proper DD…or any DD.
Thank you. I am not sure how that slipped past me. As you note, the language does not legally prevent a higher bid, even if it makes one less likely than I initially assumed.
On the positive side, Glass Lewis sided with Broadwood on essentially every major point of opposition, citing non credible management, a poorly designed go shop, and an inadequate offer price. At this stage, the offer looks doomed for rejection. So either Alcon attempts a last minute save or pushes for another delay, or the process moves into a post-break scenario. Broadwood has reiterated that it intends to call a shareholder meeting to reshuffle the board.
Glass Lewis used pretty strong language in criticizing the inadequacy of the revised offer:
https://www.bamsec.com/filing/121390025121255?cik=718937
I think there’s also a scenario 5:
Takeover is voted down and nobody wants to buy it at a higher price… Or even buy it at all.
That’s basically the worst case scenario (short of a meteor hitting Earth). It probably would only play out if China sales completely fall apart. At the end of the day, almost every scenario comes back to China sales outlook, but I agree with DT that the odds of a total bust look kinda low. Broadwood isn’t just voting the deal down, they’re effectively underwriting the standalone value and that recent $40M share purchase speaks confidence.
My base case: deal gets voted down -> stock drifts initially as arbs exit -> business recovers -> stock recovers.
Buying the common shares doesn’t seem to fit your base case very well.
Maybe buy Dec $22.5 puts for $1 and sell $25 puts further out (e.g. Dec 2026 for $3.3)?
ISS recommending shareholders vote FOR deal
https://investors.staar.com/news-and-events/press-releases/2025/12-15-2025-233507819
Two new fillings from the activists in response to ISS recommendation to vote for the merger. A couple of quotes below.
Yunqi Capital:
Broadwood:
Staar with a somewhat compelling response questioning credibility of Broadwood’s go-shop criticisms:
https://investors.staar.com/news-and-events/press-releases/2025/12-17-2025-155516264
Final arguments filed ahead of the shareholder vote. Management doubled down on discrediting the ‘mystery bidder’ (FountainVest), sharing a detailed timeline to argue there was never genuine interest.
https://www.bamsec.com/filing/119312525322104?cik=718937
Broadwood appears to be looking past the vote entirely and treat the deal rejection as a foregone conclusion. They see the standalone price target at $50/share in 2026 based on inventory normalization.
https://www.bamsec.com/filing/121390025122870?cik=718937
It seems crazy that management waited until the last minute to provide its response to Broodwood. I think things are setting up for another adjournment of the meeting.
What is a reasonable price if there is no deal? It seems most of the investors believe STAA worth a lot more than the current price.
Short term, the stock might wobble a bit as the last arbs go for the exits. But I do not expect a meaningful slide given the operational improvements in the last quarter and the likelihood that most arbs are already out. The next thing to watch will be preliminary Q4 results in January. There’s also a chance the shareholder meeting will get adjourned again.
Apparently the meeting was adjourned to Jan 6…
LAKE FOREST, Calif.–(BUSINESS WIRE)–STAAR Surgical Company (NASDAQ: STAA), the manufacturer of the Implantable Collamer® Lens (ICL) today announced that Alcon (SIX/NYSE: ALC) has exercised its right under the Alcon merger agreement to require STAAR to adjourn its Special Meeting of Stockholders in connection with the Alcon merger agreement (the “Special Meeting”). As a result, the Special Meeting, which was scheduled for December 19, 2025 at 8:30 a.m. Pacific Time, has been adjourned to January 6, 2026 at 8:30 a.m. Eastern Time. The record date for STAAR stockholders eligible to vote at the Special Meeting remains the close of business on October 24, 2025.
It’s strange that they changed the hour of the meeting from 830am Pacific Time to 830am Eastern Time (or 530am Pacific Time)? STAA is based in California.
It might be due to them wanting for vote results hit the tape before the market opens but it’s just a guess.
Then I think they are expecting that this adjournment will be the final one and that the result of the vote is likely to be negative, hence high volatility after the result is announced .
Does it mean that they (Alcon) will try to get the deal done before that? Increased offer coming?
As the meeting was adjourned by Alcon’s initiative, it kind of suggest they might be willing to consider a higher offer. However, Broadwood is skeptical that any acceptable offer will be reached:
“Nevertheless, the Special Meeting has been delayed for a fourth time. Another few weeks of advocacy and solicitation will not cure the defects of the deal.”
https://investors.staar.com/news-and-events/press-releases/2025/12-19-2025-164506909
Any insights on what should be a good stop loss from here?
Down to ~23.10 today (at time of posting). Anyone else thinking this is a good time to pick up more ahead of the new vote on Jan 6?
yes, just my opinion but I think Alcon comes in with a better offer
Picked up some as well. I think a better offer is incoming as well.
https://investors.staar.com/news-and-events/press-releases/2026/01-06-2026-134720114
Response https://www.businesswire.com/news/home/20260106480307/en/Broadwood-Partners-Comments-on-STAAR-Surgical-Shareholders-Rejection-of-the-Companys-Proposed-Sale-to-Alcon
worth entry here? sale dead in this iteration, and it doesn’t sound like broadwood is continuing the process.
Alcon’s offer was voted down, which is no real surprise. This was always the most likely outcome, though I can’t say I would have been disappointed if it had passed, given how wide the spread was. As expected, the market reaction was relatively muted, with the stock down 7% yesterday. The strong price support was also in part due to confidence exhibited by STAAR’s shareholder base, with nearly 70% of votes cast against the merger with Alcon or withheld.
The path forward is clear. Activists will move to replace the board and run a proper sale process later in 2026. If Q4 results will show continued rebound in China sales, the stock will likely move materially higher, possibly into the high $30s or even the $40s later this year. The potential upside is substantial.
All eyes are now on Q4 results, expected in February. STAAR has occasionally released preliminary figures ahead of full earnings, so if that happens this time as well, we may get an early read over the next few weeks.
If Q4 results disappoint, I think the downside would be limited. The activists could always re-engage with Alcon (if egos allow that on both sides) and attempt to bring the deal back to the table at a similar terms.
The activists, especially Broadwood, are very much staking their reputation on the eventual outcome. The current price looks like an interesting entry/add point. The bulk of the merger-break selling pressure is likely already behind us.
Given Broadwood’s long-term investment strategy why would it want to sell and interrupt its compounding? It looks like it’s kind of an accidental activist here.
what compounding are you talking about. The one that saw the share price down from $155 4 years ago to $15 in 2025? No. Broadwood is a seller at the right multiple. maybe below $40 right now, a moving target but well framed by the recent exchanges.
I was talking about intrinsic value. If Broadwood is a seller at the right multiple like you said why didn’t it sell at $155 when the stock was obviously overvalued?
They did sell some in 2021 at elevated valuation (likely in the $104-128 range).
They then bought back in 2023 (likely in the $28-39 range), and added again in 2025 at around $17.
Broadwood built its initial stake in 2004 and gradually added to it when stock prices were in the low single digits. So the 2021 monetization most likely has already recovered all of its principal invested in STAA.
well that sure is compounding, LOL! Just at a very bad return, heh.
need to double check but I read Broadwood sold in 2023 above $100.
in their preso they seem to value STAAR at $40…and were actively helping find a suitor.
You do not need Broadwood for a rerating and make money from those levels.
a confirmation of Q3 Chinese ordering rebound should be enough
thank you Snowball it was 2021 then not 2023 when they trimmed
wonder if anyone did any work on Alcon’s Dec 2025 presentation “Alcon’s Perspective on STAAR Acquisition”, especially on p16 where they discuss Broadwood’s terrible history as an activist?
https://s1.q4cdn.com/963204942/files/doc_downloads/2025/12/Update-Alcon-s-Perspective-STAA-Acquisition.pdf
I like the two footnotes on that p16 that basically say “uhhh, we’re kind of just making up numbers here”.
I had a brief look. My impression was that those cases on p16 were tiny, non-core positions handpicked from an otherwise very concentrated portfolio. In none of those cases was Broadwood acting as a public activist or fighting boards. They filed 13Ds, probably engaged quietly with management, sometimes helped to look for buyers, but that’s very different from what they’re doing now at STAAR. So saying those were “big activism failures” or smth like that is a stretch.
Lineage, IMDX, and Asterias are development-stage biopharmas that just keep failing trials which is kind of the default outcome in that space. IMDX and Asterias were very small positions for Broadwood (1-3%). Lineage was bigger, around 7-18% at various points. Comarco was basically immaterial. They even stopped filing 13Fs for it back in 2011 and mostly held warrants or prefs from what I can tell. Comarco eventually got liquidated in 2019 after losing a key patent.
STAAR is clearly the core position for them now. It’s the third-largest holding at around 22%, while the fourth-largest is only 7%. So this is a different game in terms of conviction and stakes. As dt pointed out, after all that proxy fight and blocking the merger at a large premium, the reputational hit if STAAR were to fail at this point would be enormous.
Filings today showed buying since deal termination:
Yunqi bot 750k, 5 –> 6.5% of co
Broadwood 400k for less than 1% –> 31% owner
used AI to read it so #’s might be completely wrong, there was buying tho and IMO it’s significant
https://otp.tools.investis.com/clients/us/staar_surgical_company/SEC/sec-show.aspx?Type=html&FilingId=19051885&CIK=0000718937&Index=10000
https://otp.tools.investis.com/clients/us/staar_surgical_company/SEC/sec-show.aspx?Type=html&FilingId=19049852&CIK=0000718937&Index=10000
Yes, Yunqi bought 750k shares at $21.53 on January 6 ($16.2m). Broadwood bought 406k shares at an avg. $21.68 also on Jan 6 ($8.8m).
Does anyone know what % of individual portfolios do Yunqi and Broad own (STAA)?
My two cents here:
– given we are now in the scenario 2, we need to believe on China sales recovery as it was happening in Q3.
– despite that I have concerns about valuation. If we look at the EPS of Q3 it shows 18 cents, let’s say a normal year with China recovery STAAR makes $1 per share.. it is now trading at $22, so P/E 22.. Not cheap.
– STAAR growth for upcoming years are far away IMO, and I have doubts on it because of increasing competitors. Also I don’t have a clear view on why China sales were disrupted that way and if it can happen again easily.
Thoughts?
STAA is relatively subscale, so whether one looks at net income, EBITDA, or cash flow, it screens as expensive. Phakic ICL is a relatively new and fast growing market. So STAA has always been more of a growth story with a possibility of an acquisition by a large strategic buyer that could extract meaningful synergies. A few weeks ago, Alcon itself was willing to buy STAA at a 40% premium to current prices, and it had been pursuing this deal for long time. Alcon’s interest provides the most concrete validation of valuation.
Broadwood’s valuation framework relies on sales multiples of 5.3x to 5.5x 2027E revenues, which implies a $43 to $45/share target. This range is broadly in line with STAAR’s trading levels in mid 2024, before the China issues emerged.
I’m new to the idea so please forgive me.
How do you think Eyebright Medical’s Loong Crystal will impact the company’s China sales? Specifically, are they also targeting the same patients/(higher end market) as STAA?
http://ebmedical.com/en/about/newscenter/news/2025-08-06/74.html
It is a competing product. The emerging local competition is consistent with China’s broader policy of promoting domestic alternatives. For what it’s worth, my understanding is that STAAR’s products are still viewed as superior and positioned at the higher end of the market, largely due to better biocompatibility and a longer clinical track record:
The main difference is that competitors use cheaper/lower-quality acrylic materials instead of STAAR’s patented ICL (collamer) material:
That said, this study suggests there is no material difference between the two in terms of adverse effects. Yet the study was conducted on a relatively small sample, with 28 patients in the collamer group and 32 in the acrylic group.
https://pmc.ncbi.nlm.nih.gov/articles/PMC8979746/
Pardon for my ignorance. Is there any lump sum bonus for the management and board to risk their jobs to fight against big institutional shareholders? Some board members might be at risk with board shift anyway. Does boardwood have its ppl on the board now?
Broadwood doesn’t have a seat on the board at the moment. Could you please clarify the other part of the question?
What I meant is why CEO and board go against the largest shareholders instead of working with them? Maybe they knew they would be replaced anyway.
I think a sale to Alcon triggers change of control provisions, implying immediate vesting and cash payouts for management. So they were incentivised to push it.
In other words, in the Alcon scenario, they exit with a paycheck. In the Broadwood scenario, they face a probable ouster for botching the sale process.
How difficult is it to replace the board?
STAA has 6 directors. Broadwood plans to replace 3 of them, which it sees as those most responsible for the flawed sale process. Because the board is not staggered, this is doable, and Broadwood only needs to call a special meeting, something it is entitled to do as the largest shareholder.
If Broadwood manages to replace half of the board, it would gain meaningful influence over key decisions at STAA, effectively giving it near control.
Another purch by Broadwood. Small, but a wise person once told me that buying is the complete opposite of selling. DYODD!
https://www.sec.gov/Archives/edgar/data/718937/000121390026004132/xslF345X05/ownership.xml
Why is this business still trading at a discount when the market knows that Yunqi and Broadwood are in for a board re-shuffle and therefore a higher value?
My guess at a glance is that some merger arbitrage investors are dumping… since if Broadwood is willing to sell the company, it will take more time.
Maybe it’s because they have entered into a definitive agreement with STAAR that they can’t call a special meeting or encourage any other individual to call a special meeting until June 18th.
https://www.sec.gov/Archives/edgar/data/718937/000119312526013622/d831960d8k.htm
Also, they have delisted for a while. Maybe that is another reason. Lemme know what you guys think.
More puzzling is stock drops big when broadwood joined the board. Is that because broadwood never took that kind of activist role?
Activists are not different from other investors. They can be wrong, and they are not necessarily able to turn around a struggling business or to solve the problem of weak demand for its products.
It will be unthinkable for a 30y old establishment not to do deep market analysis and have foot on the ground with all kinds of experts before adding to 30+% of position. It will be even more for a Chinese HF in China market.
Ah Yunqi is Chinese domiciled fund?! brb buying more
Established in 2018, Yunqi Capital is a Hong Kong-based hedge fund manager led by Chris.
Great comment.
Today STAAR Surgical (STAA) said that Neal C. Bradsher and Richard T. LeBuhn of Broadwood Partners and Christopher Wang of Yunqi Capital have joined its board under a cooperation pact with Broadwood, which owns 31% of STAAR. Shares of STAAR fell 3.3%.
STAAR (STAA) CEO Stephen Farrell has stepped down from the board, but will remain CEO until the end of the month, according to a statement on Thursday. STAAR Chair Elizabeth Yeu also stepped down from the board.
The STAAR (STAA) board expanded its size from six members to seven. The renewed board intends to make additional announcements regarding STAAR’s next chair and CEO in the near term.
Everyone settle down – It’s good news, just close your eyes and buy.
Broadwood, Yunqi, and STAAR’s management have reached a settlement. STAAR’s chairman and CEO will step down, and the board will be reconstituted with two Broadwood nominees and one from Yunqi.
I see this as clearly positive. It delivers the expected board reset much faster than expected and without all the hassle of a proxy fight.
The restriction on calling a special meeting until June is largely irrelevant, as a special meeting is no longer necessary.
The market’s reaction, however, is puzzling.
https://www.bamsec.com/filing/119312526013622/3?cik=718937
So broadwood and Yunqi board control is less than half. Should not post threat to their de facto control.
Hi, maybe with this new change in tne mgm , on favour of Broadwood and Yunqi, the process of adquisitio by Alcon will delay as will not meet its needs in the short term. that is why i guess share falls…. and will be there for long.
Selling accelerated today. With 70% deal rejection rate, does that mean the arbitrage money went in BEFORE the deal announcement?
Think the selling today can be explained by downgrades from Morgan Stanley and Canacord Genuity. The stock has also lost activist buying support in the short-term from them joining the board.
Just like TRUE dropped hard before the deal closing, the recent drop of STAA is strange.
The stock price reaction is not necessarily strange.
Excluding Broadwood and Yunqi, only additional 19% voted against the deal, and they accounted for less than 37% of the votes cast by disinterested shareholders (i.e., excl. B. and Y.).
The majority of disinterested shareholders who voted for the deal likely believe that Broadwood and Yunqi are just delusional and lacking the Midas touch.
It would seem that anything positive here is probably months, if not a year, away.
This seems like a prime example of a name to use longer dated calls on – upside catalyst of potential merger, uncertainty on China giving some more binary type outcomes
STAA longer dated (beyond June) calls are very illiquid and IVs very high.
How about writing near term puts and rolling monthly to collect premium? (although this is expressing a very different view from yours)
Illiqudiity is the bigger problem and will drive returns – I think 50-60% IV is fine given the setup. Similar to LQDA feels like there are fat tails here that are hard to price.
I also like writing near-term puts bc I think the time horizon here is 6-12 mos, not 1
Q4 results could be brutal.
Unfortunately, the new board/management has the same incentive as the outgoing one to paint a miserable picture.
The previous management did it to convince shareholders to sell out, and the new one will do it to lower the hurdle for a “turnaround” job.
your opinion on the board doesn’t make sense after the reshuffle and new incoming CEO, can you expand?
Q4 could be brutal, or a return to norm. Just guessing at this point.
I had called some eyes hospital in China. They said opeation number grow steady YoY in 2025.But I am still worry about the further financial result. :(
“grow steady” means flatlining from the low 2024 level?
They didn’t tell me more details but I believe at least Q2 result is consistent. Maybe more better….but don’t be too optimistic…..
I can’t edit my post…..I means Q3 result is consistent ……They said the requirment is hard……better than 2024…….
Would they have told you any different?
STAA appointed Warren Foust (current president and COO) and Deborah Andrews (current CFO) as interim co-CEOs. They will manage day to day operations while the Board conducts a search for a permanent replacement.
Any idea about why does STAA keep going down?
Seems like it’s up today on this news :
https://www.massdevice.com/fda-expands-indication-staar-surgical-evo/
Received FDA approval to expand their addressable age group from 20-45 to now 20-60 year olds
Earnings are Monday. Interesting they specifically called out China recovery as a topic for discussion.
ER is on mar 3 Tuesday AMC.
Topics on the conf call will include:
Review of Fiscal Year 2025 Operations and Financial Results
China Recovery and Operational Improvements
Inventory Normalization
Cost Discipline
Update on Manufacturing Expansion in Switzerland
Innovation Pipeline Progress
2026 Strategic Focus
Staar today announced that more than 4 million Implantable Collamer® Lenses (ICLs) have been sold worldwide, marking a milestone in the global shift away from laser-based refractive surgery.
This achievement underscores the growing global preference for lens-based solutions in refractive vision correction as patients and surgeons increasingly choose alternatives to traditional laser-based procedures, which require corneal tissue removal.
Today’s announcement was the most convoluted “explanation” i can recall. Will be anxious to see if their earnings call makes thing clear/less befuddling. $30.50 would seem to have been a lot better than post-market trading price of $16 or so.
While we wait for smarter minds’ analysis of today’s earnings, this seems sufficient:
https://finsee.ai/earnings/staa/2025/q4/en/
“I don’t think in 2026 we’re going to be seeing the hyper growth levels that we saw back 2023 and before that. Certainly, we’re working towards that. Right now, thankfully, our Board has a very long view of the company. And while we do expect nice growth globally for the company in 2026, I would caution, I don’t expect to see 20%, 25% growth, although that is definitely what we’re working to, and that is definitely the opportunity for sure.”
The Co-CEO capping growth below 20% and talking about the board’s “very long view” isn’t exactly the V-shaped recovery Broadwood sold.
There are way more countries than China so the total addressable market should be a lot more. I deem this as long term investment , not just arbitrage, if you look at broadwood’s tracking record. IMO this is a buying opportunity.
There is no sugarcoating it. STAA’s results were disappointing. Despite promotional headlines about management being “confident in China progress” and “board and leadership transitions supporting strategy execution,” the reality appears quite different.
China sales in Q4 came in at $17.5m. That’s better than the doughnut we saw in early 2025. However, it’s a massive drop from $30m in Q3’25 and well below the $40m-$60m quarterly levels that had previously been considered normal. Management attributed the Q4 weakness to turbulence around the Alcon deal, claiming some distributors returned inventory to STAA amid uncertainty over whether Alcon would become the new owner. There was also a lot of talk about inventory levels now having normalized, the implementation of a better tracking system that should prevent inventory issues in the future, and renewed focus on innovation and growth. The problem is that all these explanations lose credibility when set against the forward guidance. Management went to considerable lengths to avoid giving specific revenue projections, but analysts pressed hard, and at one point the co-CEO said:
Outside China, growth is running at high single digits. If total company growth lands around 10%-15%, that implies China sales will increase only modestly. China revenue was $77m in 2025, well below the $160m-$180m seen in 2023 and 2024. So it’s clear that any normalization will take much longer than expected or implied by the activists during the fight with Alcon. The possibility that the underlying issues in China are much more serious than management has let on also looks very real. This was always one of the risks and I mentioned it in the original STAA write-up.
So either Broadwood was also caught off guard, or they have a different game plan here that I am not seeing at the moment. Equally frustrating is that the new management team continues to rehash basically the same talking points instead of providing real clarity on what is actually happening in the business. In hindsight, Alcon’s offer looks far more attractive than the situation shareholders face today.
At this point, it seems best to move on. There may still be a long-term turnaround story here, but the special situation angle has faded. The company remains a black box, and relying on the activist clearly did not work out. I am marking a 22% loss on the position after three months.
Press release: https://www.bamsec.com/filing/71893726000005?cik=718937
Question – isn’t this a broken thesis if one purchased the stock for the original idea of a takeover?
The situation had multiple angles, as outlined in the scenarios above. The Alcon takeover was blocked, and the China recovery story appears to have faded. What remains is the long-term turnaround, but that is not a thesis I am willing to hold for.
Yes all very well laid out scenarios – thank you. Terrific insight and research. I wanted to confirm for myself that the scenario I was in it for has not played out and therefore I should sell and revist with a fresh perspective (or not). Portfolio management! On to the next opportunity!
Go-shop process has still not been started by Yunqi and Broadwood. Why is everyone panicking?
Also, did Broadwood and Yunqi exit the position.?
No.
Browdwood is a really long term concentrated stakeholder.
Broadwood is adding more
https://www.bamsec.com/filing/91957426001617?cik=1278387
Glad they committed another $12mm. I trust what they said in the public letter and willing to hold for at least 2 years.
Whalewisdom is not working the usual way. Any other tool/site that I can use for tracking STAA holdings by Broadwood and Yunfi?
Their trades must now be reported via Form 4 filings within two business days, no? so the usual SEC website or similar should help you.
STAAR Surgical announces preliminary net sales for first quarter 2026
Apr 08, 2026
it expects first-quarter net sales to exceed $90 million, more than double from $42.6 million a year earlier, driven largely by strong performance in China.
The company said China accounted for the majority of the increase, while the Americas posted continued double-digit growth.
STAAR added that improved sales and a lower cost structure are expected to lead to a significant improvement in adjusted EBITDA for the quarter.
Sales in parts of the Middle East and other regions in EMEA and Asia-Pacific were affected by geopolitical and macroeconomic challenges, the company said, warning that continued volatility could weigh on growth.
The company noted that first-quarter 2025 sales were impacted by minimal shipments to China as distributors reduced excess inventory, which it said has now returned to targeted levels.
Consensus revenue for Q1 is $67.59M.
STAAR said the figures are preliminary and unaudited, with full results to be reported in early May.
@dt what was the real reason that you exit this bet so early?
See my comment on Mar 4, where I have elaborated on the situation after Q4 results.
Thanks for the elaboration. Very insightful.
Wow what a move. Glad I held on!!
STAA Q1 numbers were super strong, the complete opposite of what management communicated after Q4 results. Basically just a month ago, management said:
“And while we do expect nice growth globally for the company in 2026, I would caution, I don’t expect to see 20%, 25% growth”.
A month later they report a 100%+ growth in revenues YoY with majority of it driven by rebound in China sales. No idea if this is just a one off quarter or a new maintainable level of quarterly sales that we are going to see for the rest of 2026. Conflicting communication from management within such a short time period makes it impossible to assess what is really happening.
As the management said the lower q4 number was due to uncertainty with the acquisition, they probably were not sure how much revenue will rebound once dust settles. Also q1 2025 was a very soft quarter . So could be a one-off growth.
If the sale normalizes at this level, what instrinsic price will you give?
They said that in early March, so they prob knew of the rebound. Insiders bought too, broadwood but it counts
I suspect this growth is one off. The key is how much growth they can achieve in the next 2 quarters and keep cost in check.
https://investors.staar.com/~/media/Files/S/staar-surgical/press-releases/260512-1q2026-shareholder-letter-and-earnings-release.pdf
Congratulations to all of us who held on….I earned a new car in the last 9 minutes 😁
Do you recommend any other good candidates ?
STAA fucking flying, this mgmt team is a joke with their sandbagging then Broadwood buys. The rebound thesis is playing out in spades. Still can’t believe how conservative their statement was given the facts playing out right in front of them.
First Quarter 2026 Financial Overview
•
Net sales of $93.5 million, up 119.6% Y/Y
•
Net sales excluding China of $46.1 million, up 6.0% Y/Y
•
Gross margin at 73.6% vs. 65.8% a year ago
•
Net income of $5.2 million or $0.10 per diluted share, compared to a net loss of $(54.2) million or $(1.10) per diluted share a year ago
•
Adjusted EBITDA1 of $24.4 million or $0.48 per diluted share, compared to Adjusted EBITDA1 loss of $(26.3) million or $(0.53) per diluted share a year ago
Fellow Shareholders,
STAAR is off to a strong start in 2026, as reflected in our first quarter financial results. We have made meaningful advancements against our core objectives of Revenue Growth and Profit Expansion, and we expect to advance Product Innovation over the balance of the year. In the approximately 100 days since we were appointed to lead the Company, our focus has been clear: improve operational execution and position STAAR to deliver sustainable, long-term value creation.
We are encouraged by the continued engagement from employees, surgeons, distributors, and investors, and by how the organization has come together following a challenging 2025. STAAR remains uniquely positioned as the global leader in lens-based refractive surgery, and our recent progress reinforces that long-term opportunity.
Key 2026 Operational Highlights:
•
Record first-quarter net sales of $93.5 million
•
Surpassed the milestone of 4 million ICLs sold globally
•
Return to growth in China, with distributor inventory at or below contractual levels
•
Strong launch of EVO+ ICL in China
•
Double-digit U.S. net sales growth with quarterly net sales surpassing $6 million
•
Return to profitability with improving margins
Any other turnaround stocks are you watching?
KKR – compounder
Glad I held on. STAA ws a buy when puke out occurred earlier.
I see a bit over 20% short float. Continuing to hold hoping for a short squeeze isn’t my favorite reason for owning, but rally could continue.
Short % is less than 20% by now.
Wasn’t the AGM scheduled for 15th June 2026? Anyone attended it?
any thoughts @ dt