Current Price: $1.50
Target Price: $1.80-$1.90
Potential Upside: 25%
Expected Timeline: Q3 2026
Waldencast is a skincare and cosmetics company with two brands: Obagi Medical, a high-end skincare line, and Milk Makeup, a mid-end cosmetics brand aimed primarily at Gen Z. Despite a nearly 50/50 revenue split and almost identical margins, Obagi has always been considered the crown jewel given its more stable growth and premium positioning.
On June 1, WALD announced the sale of Obagi to Bridgepoint Group for $366m in cash, plus $30m in vendor notes and up to $64m in earnouts.
The setup here is simple: WALD currently trades at pro-forma net cash, with an EV of just $1m. In other words, investors get the remaining Milk Makeup business and the optionality on the earnouts almost for free. If the earnouts pay out in full, the EV drops to negative $65m. I expect a significant portion of the cash proceeds (after debt paydown) to be returned to shareholders, though management has not communicated on this front yet. There is a decent chance that closing of the sale or an announcement of a large capital return will propel the share price higher.
It seems to be a favorable time to enter this trade as the stock has sold off since the post-announcement pop. It hovered around $1.70-$1.90/share for a couple of weeks, versus $1.50/share currently and $1.30/share before the sale was announced. The current levels, the downside looks fairly well protected, creating an asymmetric opportunity.
The buyer, Bridgepoint, is a large UK private equity firm with $100bn in AUM. The transaction is conditioned on US antitrust approval and pharma regulatory approvals in several states. Bridgepoint already owns a few dermatology assets, but they’re concentrated in Europe, and its US exposure seems very limited. Obagi itself is a relatively small business, with $160m in annual revenue. Shareholder approval is not required. I think that the closing of Obagi sale is pretty much guaranteed, and is expected in Q3.
Here’s how the EV calculations stack up:
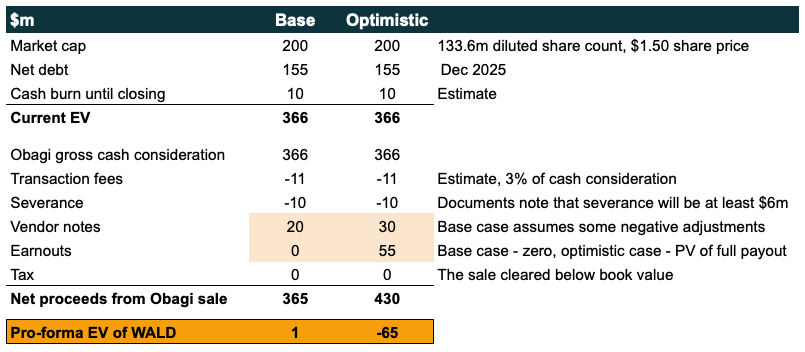
NOTE: my net debt estimate could be a bit too conservative. I assume the maximum prepayment penalty on full principal, yet it might still turn out lower (it’s not fully clear). For debt, I take the principal amount of $151m plus $3.4m of unamortized issuance costs as of Dec’25, plus a 20% prepayment penalty. The cash stood at $30.4m as of Dec’25.
Two factors might partially explain the market’s skepticism on WALD. The first is uncertainty over whether management will return any sale proceeds to shareholders. The second is that the outlook for the remaining Milk Makeup business is murky, as the business is currently in a turnaround phase.
Both of these concerns are overblown. I think that the market is underappreciating the odds that WALD makes a large capital return after the sale and Milk Makeup, at worst, is a zero / costs you nothing. A closer look on all of these moving parts follows below.
The existing discount is likely compounded by a few additional optical factors. WALD is an ex-SPAC, which makes it an automatic pass for some investors. The company was recently involved in an SEC investigation related to certain historical financial restatements of Obagi, which concluded without penalty in April. The current CEO and some other executives will depart with Obagi, which does not look great on paper, but is largely irrelevant in practice as the founder of Milk Makeup business has been put in place to lead the turnaround.
The case for a capital return
The sale announcement firmly committed to only one use of proceeds so far – repaying outstanding debt. Beyond that, management noted a focus on reaccelerating Milk Makeup’s growth. The only reference to potential shareholder distributions was: “Any further allocation of transaction proceeds remains subject to review by the Board of Directors.” While such vague communication is less than ideal, the board still kind of hinted that capital return is under consideration.
More importantly, a few other factors suggest that a large capital return is far more likely than it appears: high insider ownership, and the asset + management shake-up that comes with the Obagi sale.
Insiders own 47% of WALD. The company went public in 2022 through a three-way SPAC merger with Obagi and Milk Makeup. The SPAC sponsors still control 25% of Waldencast and have run the company ever since, with Michel Brousset as CEO and Felipe Dutra as chairman. Another 22.3% stake belongs to Cedarwalk Skincare, Obagi’s former owner. Cedarwalk still operates Obagi in China and pays WALD royalty fees. Cedarwalk also has a representative on Waldencast’s board.
Most of these insiders were likely drawn to WALD primarily because of Obagi, and the sale leaves them in an awkward position. CEO Brousset and several other executives will depart to continue running Obagi under Bridgepoint’s ownership. They will have nothing more to do with the management of Milk Makeup, yet will retain a large stake in it. Cedarwalk, meanwhile, will be left stranded with a large ownership in a struggling cosmetics company that no longer has any connection to Obagi. My point is that neither Cedarwalk nor the departing executives have a compelling reason to leave a large cash pile sitting at WALD. They own around 30% of WALD combined and have clear incentives to push for a meaningful capital return.
The remaining insiders and SPAC sponsors who will stay with Milk Makeup also have large stakes, so the incentives of all major shareholders are broadly aligned. Even after repaying debt and setting aside $50m-$80m in cash for the remaining business, WALD would still have 40-60% of its market cap in (essentially excess) cash, and any meaningful capital return would send the stock higher.
I’d expect to hear something on the capital allocation front by mid-August at the latest, alongside the H1 2026 report, and ideally before it.
Milk Makeup turnaround
The sale of Obagi is a result of a year-long strategic review. The company likely wanted to sell both brands, however, Milk Makeup hit a rough patch in H2 2025 (sales declined 19% YoY), which probably delayed those plans. Milk Makeup will likely be sold too eventually, though the timing depends on business performance.
WALD provides limited segment disclosures, and historical financials are only available through 2023.

Note: the EBITDA figure is significantly adjusted, and actual cash flow from operations was negative in all three years (-$12.8m in 2025). Capex is minimal.
Management attributed the recent weakness in Milk Makeup segment primarily to the international division, blaiming softer demand and high retail inventory levels. The brand-level issues are hard to pin down from the filings alone, but this beauty products reviewer on YouTube (admittedly an anecdotal reference) argues that Milk’s problems have stemmed from its flagship products (Hydro Grip Primer and Jelly Cooling Stick) being copied by competitors, ineffective marketing, recent launches failing to gain traction, and an expansion into Ulta Beauty stores that has diluted brand perception among their target audience.
So there are indications that the business may have been mismanaged under the current management, who were likely predominantly focused on Obagi and who are now leaving to run the business under Bridgepoint ownership. To fix the issues and lead the turnaround, in H2 2025 WALD has brought back Milk Makeup’s founder, Mazdack Rassi, as president of the segment. Rassi had founded the business back in 2016, and then stepped away from the brand following the SPAC merger.
If the turnaround starts gaining traction and/or the company is eventually sold, the upside could be significant. Applying an undemanding 1x multiple to FY2025 sales implies 55% gain from current levels. For what it’s worth, Obagi was sold at 2.3-2.8x FY25 sales.
For the near term, even if RemainCo continues to burn cash while the turnaround is in process, the brand value and turnaround optionality alone should be worth something.
Earnouts optionality
The $64m earnouts from the Obagi sale have two components.
The first part can pay up to $10m. It is conditioned on Obagi’s net revenue in 2026, excluding the newly launched Saypha injectables line. The target range is $185.2m-$190.2m, with the payment scaling linearly. Obagi generated $161.6m in 2025, growing 8.3% YoY. Hitting the floor target requires 14.6% growth, while hitting the ceiling requires 17.7%.
The second part pays up to $54m, based on Saypha injectable revenue in 2027. The payout range runs from $47.5m to $50.5m. Saypha is a dermal filler launched in March 2026 with no disclosed financials yet.
The revenue targets for both parts seem fairly aggressive, which is why I put the earnouts at zero in the base case EV calculations above. The incentives behind such CVRs are also usually not well aligned. That said, some optionality clearly exists. Bridgepoint already owns several dermatology and CDMO assets, primarily in the EU, giving it a network of connections among doctors and clinics. It is not clear what percentage of revenue Obagi generates in the US versus the EU, but the US is likely a large portion, since the physician-dispensed channel was historically the core of the brand’s business. The fact that the sale is conditioned primarily on US regulatory approvals (and not EU) suggests the same. If Bridgepoint plugs Obagi into its derma network in the EU, it could meaningfully boost sales growth and help reach the CVR targets.
Specifically, Bridgepoint holds an investment in Vivacy, a hyaluronic injectables maker mainly in the EU, similar to Saypha, on which the second part of the CVR is conditioned. It also holds Diagnostikcentrum, the largest dermatology clinic chain in Sweden. Beyond that, its portfolio includes a few CDMOs and compliance service companies for the life sciences industry, giving it a decent network in the EU derma/pharma sector.
Well that was quick
Sale of Obagi announced as completed, valued at $460m. Price up to $1.80 after hours.
I am removing WALD from active cases. Net proceeds from Obagi came in lower than anticipated, and the stock has moved up since the write-up. RemainCo is now valued at around $76m, against just $1m two months ago. The easy money has been made. What remains is a more execution-dependent play on an uncertain timeline. Even if Milk Makeup were sold at 1x FY2025 sales, that is only 15% further upside from here.
In the announcement of the Obagi sale closing, management said nothing new on capital returns, only that debt has been repaid, that it will continue to invest in RemainCo, and that any further allocation of proceeds remains subject to review. The company received the vendor notes in full with no adjustments, while the debt appears to have been repaid with the full prepayment penalty, as expected. Management values the vendor notes at $21.8m and the earnout at $20.8m.
The disappointing part was that RemainCo’s pro forma net cash as of December 2025 came in at just $143m. I had previously expected the comparable figure (before this year’s cash burn) to land at $190m = $345m of net cash proceeds less $155m of net debt. Part of the gap is explained by $25.4m of cash that transferred with Obagi. I had not anticipated this, as the transaction was described as being done on a “cash free, debt free basis”, but it turns out that WALD was compensated for Obagi’s cash in the consideration. So it’s an oversight on my part. Where the other ~$20m went is not clear. There appear to have been further “estimated purchase price adjustments made at closing”, and transaction expenses probably ran a bit higher as well.
The current market cap is $231m, up from $200m at the time of the write-up. Assuming the same $10m of cash burn until closing, net cash today sits somewhere around $133m. Taking the vendor notes at management’s value and the earnout at zero, RemainCo would be valued at $76m, against $110m of sales last year.
https://www.bamsec.com/filing/184019926000080?cik=1840199