Potential Takeover: 9%+ spread (at A$5.57)
Priority Technology is a payments software company that is currently reviewing the non-binding $6.00-$6.15/share privatization offer from its founder and chairman. The chairman, Thomas Priore, owns around 55% of PRTH, while his brother has a further 5% stake. The offer looks too low, coming in at roughly 6x FCF, and well below the $15-$20/share price target of activist Buckley Capital. Buckley and another activist, Steamboat Capital Partners, have voiced opposition to the current bid. My own more conservative sum-of-the-parts (SOTP) valuation lands at $10/share. There’s a chance the offer will be raised.
I have previously covered PRTH in November 2025 (you can find the write-up here) and closed the idea two months ago after +30% run-up in the share price. The stock moved well above the offer range to $7+/share without any news. At the time, I wrote:
I am taking my chips off the table. The stock already trades at a 16% premium to previous low-ball bid from founder/controlling shareholder. The offer was made eight months ago and the review is still ongoing. I have not seen any other news/rumors about it. So it is not really clear what has driven the PRTH re-rating over the last couple of months. But, I am happy to pocket 30% return and move on. Might revisit if the shares drop below bid levels (as has already happened a couple of times).
Over the last few days, the stock has dropped sharply, moving from a 10% premium to a 9% discount.
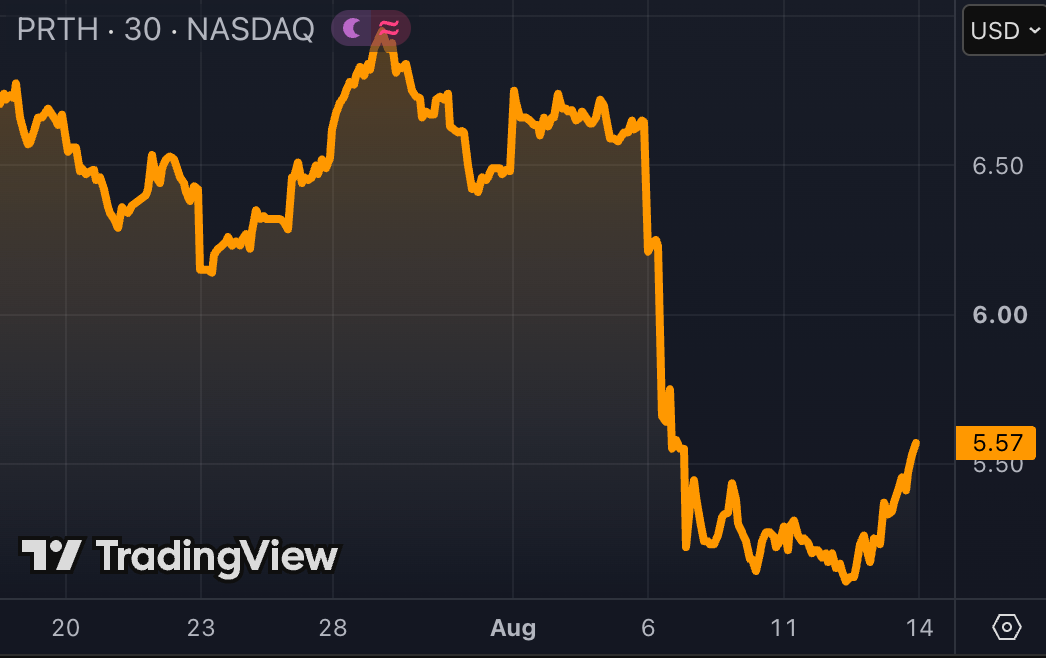
The drop was prompted by Q2 results that came out on August 6. The earnings were not particularly bad, just a bit soft on the margins/profitability side. Management reaffirmed its prior 2026 guidance ranges for revenue ($1,001m-$1,004m) and adj. EBITDA ($230m-$245m), but guided revenue to land near the top of that range and EBITDA near the low end.
I have covered the individual segment results in the section below, but overall not much really happened in Q2. I do not think this print will have any effect on chairman’s intentions. The actual shift in fundamentals was minimal, and it is not as if PRTH suddenly stopped being an attractive (and cheap) privatization target, especially given how lowball the current offer is. The company is still printing cash (around $1/share in FCF per year) and growing.
So I think the share price drop was mostly due to PRTH’s leverage, general volatility, and some fatigue among investors who had probably expected an update on the privatization alongside the Q2 results.
The company carries a fair amount of debt (3.8x net debt/EBITDA), so EV has actually fallen by only ~7%.
Such volatility is not unusual for PRTH. Historically, the stock has had a number of violent reactions to earnings, even over the last two years (see the chart below). In Q3 2025, for example, the stock fell 30% when 2025 revenue guidance was trimmed by only 2% and EBITDA guidance was left unchanged. Chairman’s privatization offer came just days later.

Given how the chairman used opportunistic timing for the initial bid, I would not be surprised if he used the current price weakness as an opportunity to finalize the offer.
The main concern in this situation is the prolonged timeline. The special committee review has been ongoing for ten months already. That’s usually not a great sign. There is a saying (I don’t remember by whom) that “good assets transact fast.” While that holds generally, there are historical precedents to the contrary, for example, WOW’s review took 15 months, and the initial offer was ultimately raised (covered on SSI here). Also, PRTH is a controlled company, so speediness is not that relevant for the buyer, as he’s not competing against other potential bidders. He knows the offer is low, and as chairman he has full visibility into how the business is tracking from quarter to quarter. If he expects a soft print or two along the way, waiting costs him nothing and only improves the optics of the offer.
Another thing to keep in mind is that the chairman owns a controlling stake, and minority shareholder approval is not mandatory. The higher bid case rests almost entirely on whether the special committee will push for an improved offer.
If the deal ultimately falls through, it is hard to say where the stock would settle. The company is cheap at around 5.5x FCF, so there is some price support from the fundamentals. One analyst on the latest conference call even suggested the current offer might be acting as an overhang on the share price. Despite all of that, PRTH is still very levered and prone to big swings. If the privatization does not materialize, the initial stock reaction would likely be sharp, and it’s anybody’s guess how long would it take for fundamentals to eventually pull it back up. This is ultimately a binary bet and should be sized accordingly.
More on Q2 results
Historical financials can be seen in the table below:

Merchant Solutions is PRTH’s legacy business and its largest by revenue. It is the classic “merchant acquiring” operation, which helps businesses such as restaurants and retailers accept credit cards and other electronic payments. Merchant Solutions held up strongly and steadily in Q2, business as usual. The segments that took a hit were Payables and, to a lesser extent, Treasury Solutions.
Payables provides accounts payable automation software. It’s by far the smallest, but fastest growing segment of PRTH. While segment revenue grew +21% in Q2, adj. EBITDA margins shrank to 10%, down from 17% in Q1 and 14.5% last year. Management did not explain the drop in detail, but attributed it mostly to a revenue mix shift toward buyer-funded transactions (where the buyer, not the supplier, pays for payment processing).
Buyer-funded transactions carry lower reported margins due to certain accounting rules, under which PRTH has to leave interchange fees inside the revenue line (which is not the case for supplier-funded revenues). Recent interchange fee increases by Visa and Mastercard made this worse, inflating the revenue line further, but compressing the reported margin for the buyer-funded transactions. The key point, however, is that at least this margin pressure from the mix shift was mostly optical rather than a real deterioration in the business.
Treasury Solutions saw some margin pressure as well, with adj. EBITDA margin at 78.4% versus 79.4% in Q1 and 84% last year. Management pointed to recently signed clients that carry lower margins, though the plan is to cross-sell higher-margin products as those relationships expand. The other reason is the segment’s two growth businesses, Passport (embedded banking) and Priority Tech Ventures (a tiny VC arm for embedded software platforms). Both are growing very fast (Passport was up 125% YoY in Q2 and Priority Tech Ventures grew +400%), but both run at 30%-40% gross margins (compared to 89% for the total Treasury Solutions segment), so they drag down the average as they scale. This, again, does not look like major fundamental deterioration, but rather normal volatility along with some impact from the business mix shift.
Andrew did a pod on PRTH with Zack Buckley from Buckley Capital. Buckley is the main activist in this setup and has been publicly pushing for a higher privatization price. A few highlights:
– Zack gives a nice breakdown of Treasury Solutions, which is a much higher quality business from the remaining segments, with highly recurring revenues and ~80%+ EBITDA margins. Treasury now generates roughly 60% of PRTH’s EBITDA, so the point is that valuing consolidated PRTH like a normal merchant acquirer misses a large part of the value. Zack thinks businesses with these software-like economics and growth can still warrant double-digit EBITDA multiples.
– Payments peer Payoneer was acquired at ~8.3x EBITDA in June, right in the middle of the payments/SaaS selloff, which makes it the most useful recent mark for PRTH’s payments business. The deal was announced six months after Priore’s original bid, potentially handing the special committee a fresh valuation mark and stronger leverage to push for a higher price. Applying Payoneer’s ~8.3x EBITDA multiple to PRTH as a whole translates to $12/share, even without giving Treasury the higher multiple it arguably deserves.
– Zack still maintains the same ~$17-19/share SoTP from Buckley Capital’s prior public letter. He does not walk through the full valuation bridge on the pod, but notes that the SoTP uses what he considers a very conservative multiple for Treasury.
– On why the review has taken so long, one of his thoughts was that the June Payoneer transaction may have introduced a fresh valuation mark and gave the negotiations a new momentum. Zack admits the timeline has been long, though not unusual for a serious process, and does not think the delay itself means the deal is dead.
The share price went up 6% yesterday. The spread to the current bid narrowed to 4-7%.
Original activist letter: https://www.prnewswire.com/news-releases/buckley-capital-advisors-issues-statement-regarding-controlling-shareholders-take-private-proposal-for-priority-technology-holdings-inc-302620153.html
The podcast: https://www.youtube.com/watch?v=r_jdLMU6S7Y
PRTH spread is gone, with the stock now slightly above the low end of Priore’s offer. Overbid optionality is getting priced back in.